Insurance for Edinburgh Tenement and Period Properties: What Owners and Landlords Need to Know
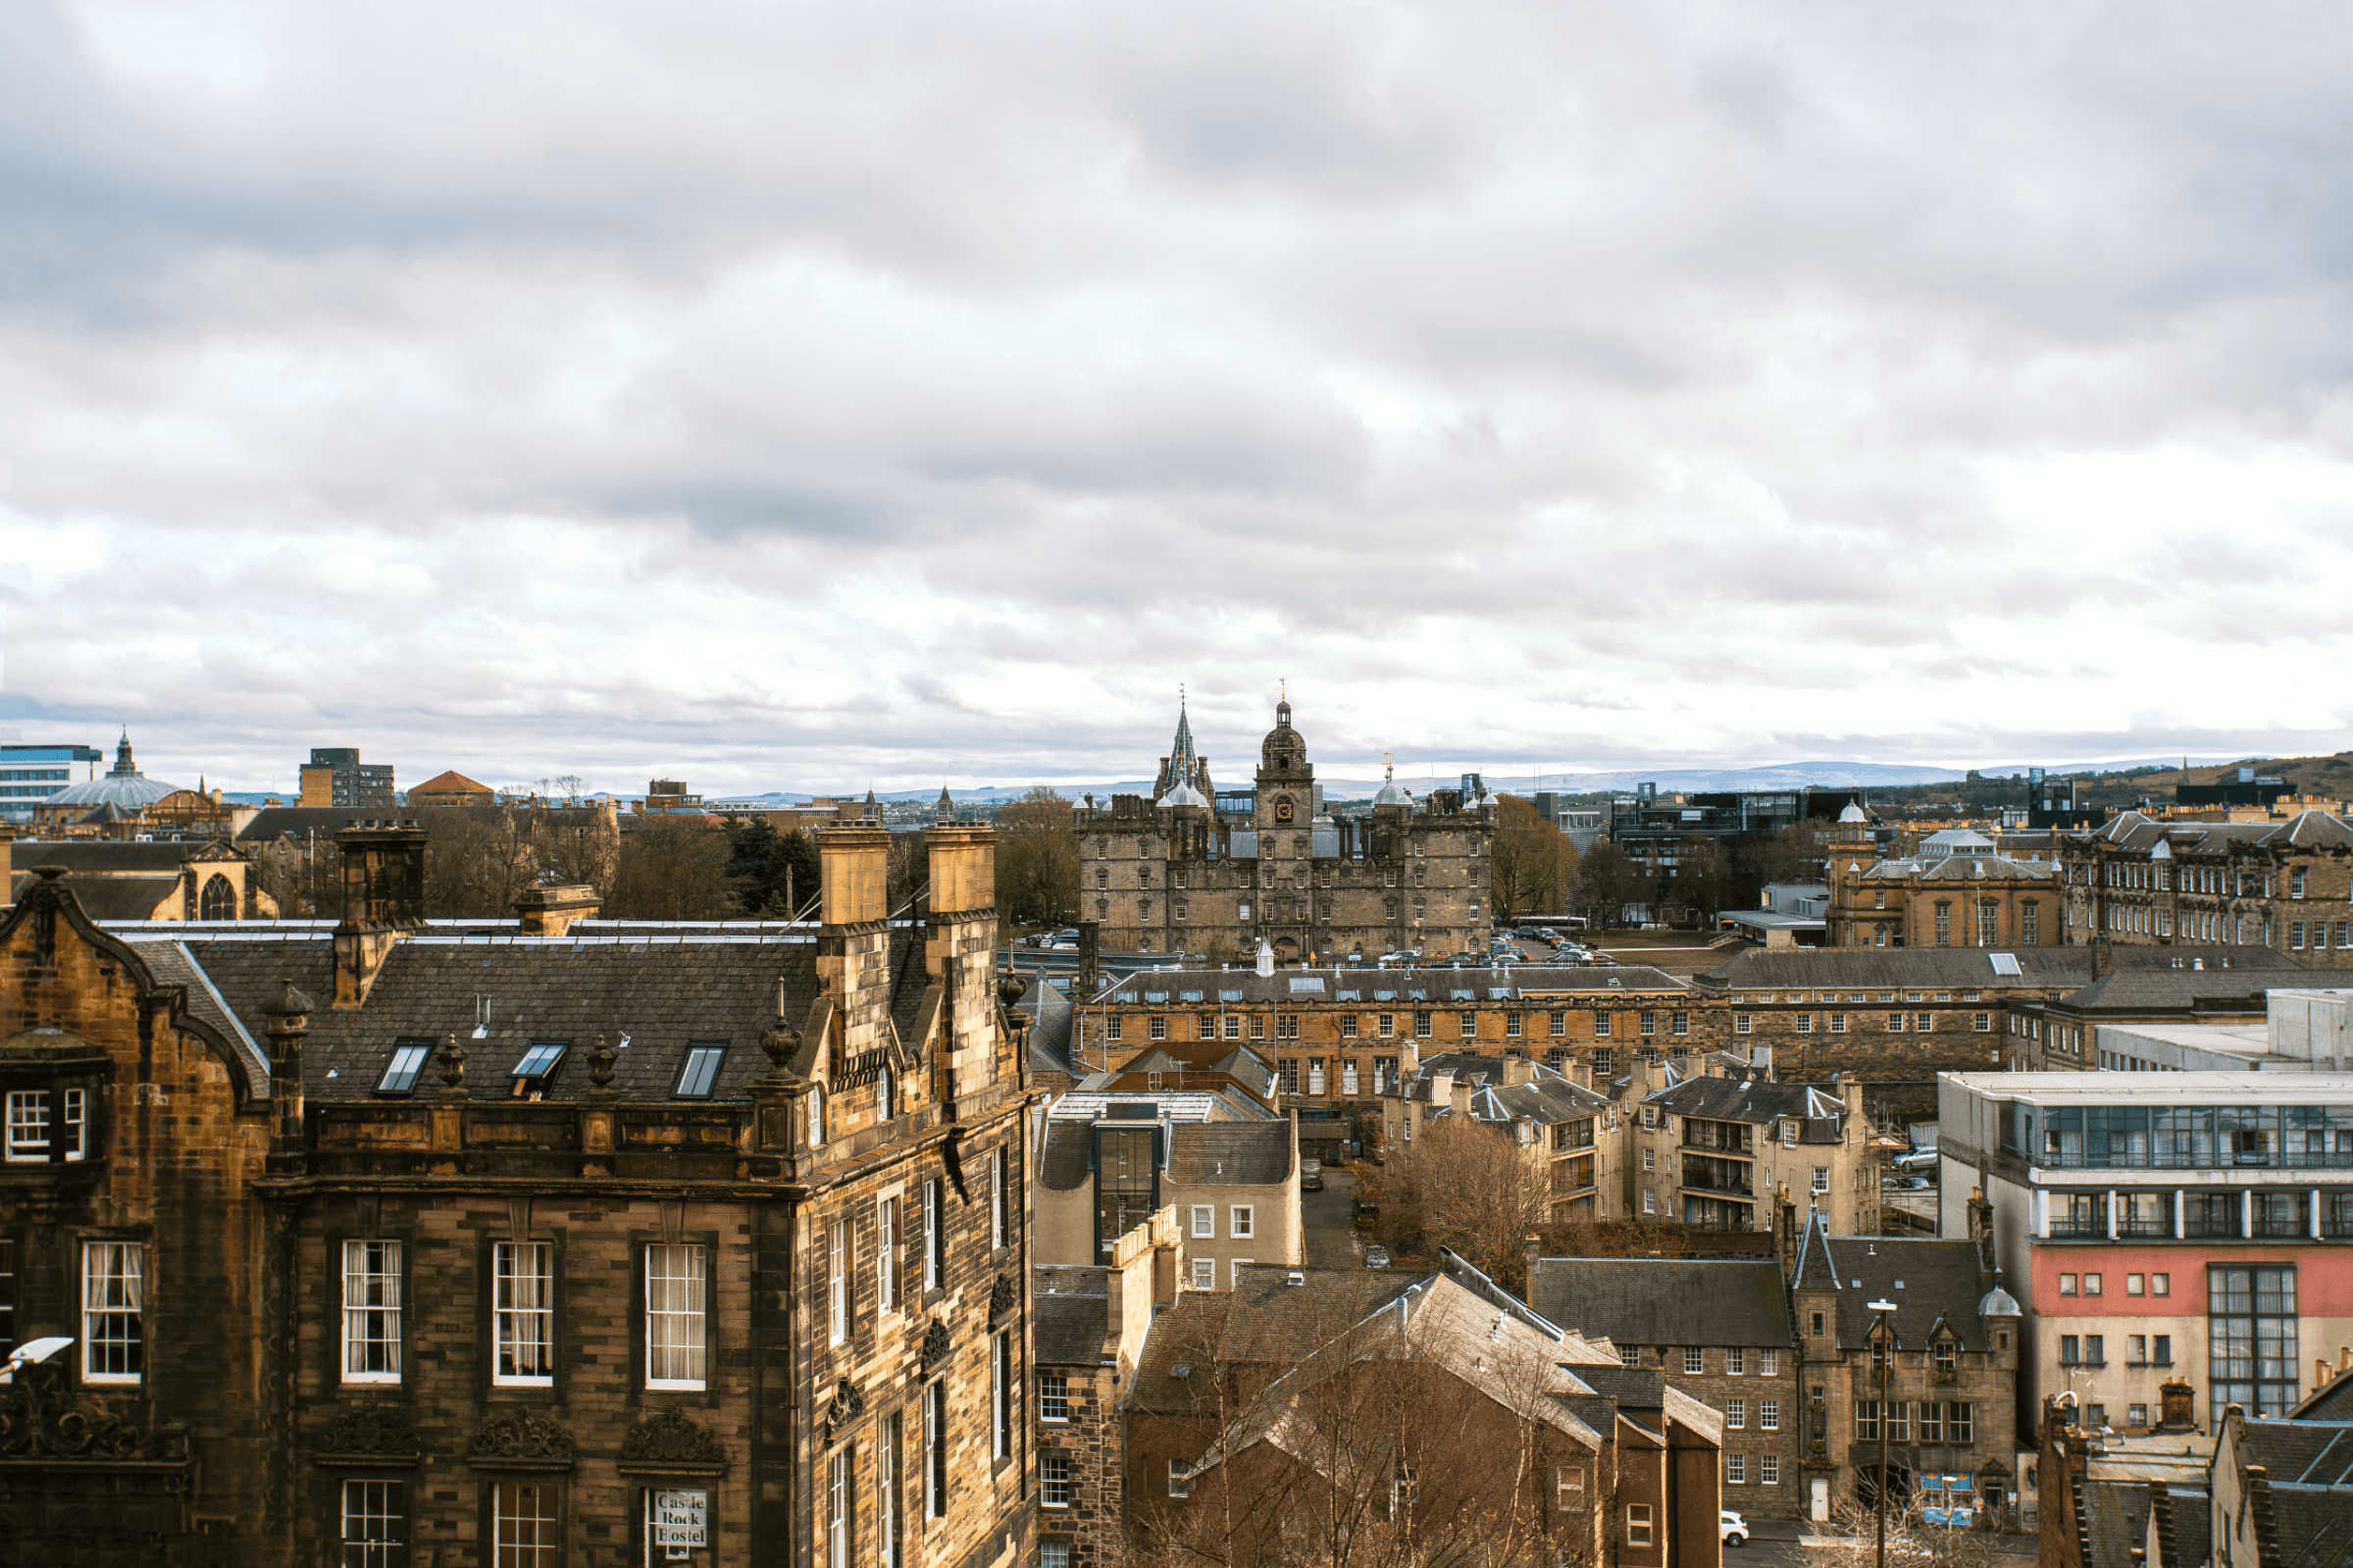
Edinburgh is a city of tenements, Georgian terraces and Victorian villas, and insuring that kind of property is not the same as insuring a modern semi. Shared roofs, communal stairs, listed-building rules and conservation-area restrictions all change what cover you need and where the gaps appear. This guide explains what owners and landlords of Edinburgh period property should understand before they buy, and where the usual off-the-shelf policy tends to fall short.
It’s also worth saying that period property isn’t a problem to be insured around, it’s an asset to be insured properly. These are some of the most desirable homes in the country. The aim isn’t to pay more for the sake of it, but to make sure that if the worst happens, the building can be put back exactly as it should be, with the right materials and the right craftsmanship.
Why period property is a different insurance proposition
Older buildings cost more to put right. Lime mortar, sash-and-case windows, decorative cornicing, slate roofs and stone façades all require specialist materials and skilled trades to repair properly and a like-for-like reinstatement after a fire or flood is far more expensive than for a modern building. The single most common mistake we see is a period property insured for too low a rebuild value, because the owner used a modern build-cost estimate. If the sum insured is wrong, even a valid claim can leave you badly short.
The shared-roof and common-repairs problem
In a tenement, the roof, the common stair, the gable walls and often the building’s structure are shared between the flat owners. Repairs to these common parts are usually a collective responsibility, frequently governed by the title deeds and by Scotland’s tenement legislation. That creates two practical insurance questions every flat owner should ask:
- Is the whole building insured, and by whom? — Many tenements have a single block (common) buildings policy covering the entire structure, often arranged by a factor. Others rely on each owner insuring their own flat, which can leave dangerous gaps where shared elements aren’t clearly covered by anyone.
- Does your cover match your share of liability? — If you’re responsible for a share of common repairs, your policy and sum insured need to reflect that, not just the four walls of your own flat.
Getting this wrong is surprisingly common, and it tends to surface at the worst possible moment, after storm damage to a shared roof, when owners discover the building was under-insured or the responsibility was unclear.
Listed buildings and conservation areas
Large parts of Edinburgh sit within conservation areas, and many buildings are listed. That affects insurance in a few ways. Repairs may legally have to use specific materials and methods to preserve the building’s character, which increases reinstatement costs, your rebuild figure needs to allow for that. You may also need listed-building consent for certain works, and a standard policy won’t necessarily account for the extra cost and time that compliant repairs involve. If your property is listed or in a conservation area, your insurer needs to know, and your cover should be built around it.
Sash and case windows and other period features
Original sash and case windows, stained glass, ornate plasterwork and period joinery are part of what makes these homes special, and they’re costly and specialised to repair or replace. A policy that only contemplates standard double-glazed units won’t reflect the real cost of putting a damaged period window right. It’s worth making sure your cover recognises the features your property actually has.
Extra considerations for landlords
If you let a period property, you’ll need landlord-specific cover rather than standard home insurance — typically including property owners’ liability, loss of rent and cover that contemplates tenants rather than owner-occupiers. In a tenement let, you also need clarity on how your policy interacts with any block buildings policy, so you’re neither doubling up nor leaving the shared structure uncovered.
A quick checklist for period-property owners
Before you renew, it’s worth confirming a few things: that your rebuild value is based on a proper reinstatement assessment rather than market value or a modern build cost; that you know exactly how the building’s shared structure is insured and by whom; that your insurer is aware of any listed status or conservation-area restrictions; and that period features like sash-and-case windows are genuinely reflected in your cover.
If you can’t answer any one of those with confidence, that’s the gap to close. Period property rewards a bit of diligence here, the cost of getting it right is small, and the cost of getting it wrong only shows up after a fire, a flood or a storm, when it’s too late to fix.
Frequently asked questions
How do I work out the right rebuild value for a period property?
Not from the market value or a modern build cost — both are misleading for period property. A proper reinstatement assessment that allows for traditional materials and skilled trades is the reliable route, and it’s the single best way to avoid being underinsured.
Who insures the shared roof in a tenement?
It depends on the building. Many tenements have a single block buildings policy covering the whole structure, often arranged by a factor; others rely on each owner. The crucial step is confirming which arrangement applies to your building so the shared parts aren’t left uncovered.
Does my insurer need to know the property is listed?
Yes. Listed status and conservation-area rules affect how the building must be repaired and therefore the cost — so your insurer needs to know, and your sum insured should reflect compliant repair costs.
Is standard home insurance enough for a period flat?
Sometimes, but it frequently isn’t — standard policies can underestimate rebuild costs and overlook shared-structure responsibilities. It’s worth having the cover reviewed by someone who understands period property.
Will my premium be higher for a listed building?
It can be, because compliant repairs using traditional materials and skilled trades cost more — and your rebuild value should reflect that. The right approach isn’t to hide the listing to save money, but to insure the building properly so a claim can put it back correctly.
Where local knowledge actually helps
This is one area where an Edinburgh broker earns their keep. Our group includes a specialist sash-and-case window company and a building firm that works on exactly these properties, so we understand period buildings from the trade side as well as the insurance side. That means we can help set a realistic rebuild value, make sure shared-structure responsibilities are properly covered, and arrange cover that reflects listed-building and conservation requirements, rather than a generic policy that quietly ignores all of it.
If you own or let a tenement or period property in Edinburgh, talk to us before you renew, it’s worth getting this one right.